Education Loans in India: Interest Rates, Subsidy Schemes and How to Apply
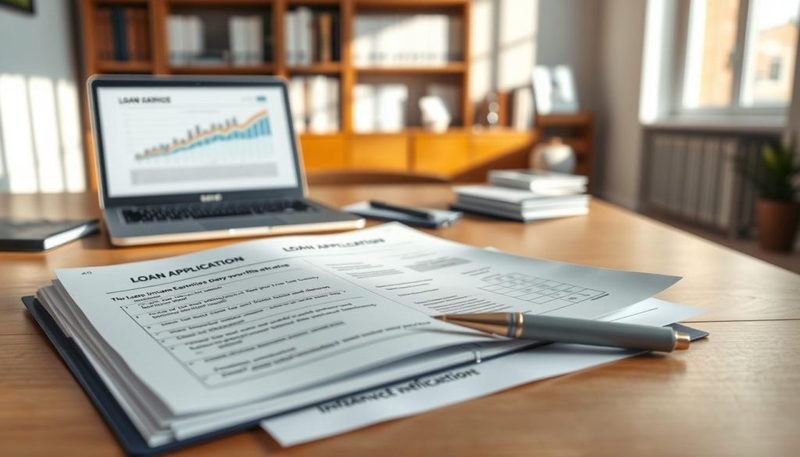
When the admission letter arrives from a dream college but the fee structure runs into lakhs, education loans bridge the gap between ambition and affordability. Indian banks disburse thousands of crores in education loans annually, and government subsidy schemes make them genuinely affordable for eligible families. Yet many parents fear loans, misunderstand the terms, or apply too late. This guide explains interest rates, the subsidy schemes that cut costs, and the application process step by step.
How education loans work: the basics
Education loans cover tuition, hostel, books, equipment, travel and other course-related expenses. For loans up to Rs 4 lakh, no collateral or third-party guarantee is typically required; between Rs 4 lakh and Rs 7.5 lakh, a third-party guarantee is usual; above Rs 7.5 lakh, collateral (property, FDs) is generally required. Repayment starts after the course plus a moratorium period (usually 6-12 months after completion or getting a job), with tenures of 10-15 years. Interest rates from public sector banks typically range from around 8 to 12 per cent depending on the loan size, collateral and the institution’s reputation — premier institutes often get preferential rates. Crucially, interest paid on education loans qualifies for tax deduction under Section 80E for eight years, with no upper cap.
Subsidy schemes: CSIS and state top-ups
The Central Sector Interest Subsidy (CSIS) scheme is the most important cost-cutter: for students from families with annual income up to Rs 4.5 lakh, the government pays the entire interest during the moratorium period (course duration plus one year) on loans from scheduled banks for professional and technical courses in India. This effectively makes the study period interest-free for eligible families. Several states add their own interest subsidies or guarantee schemes on top. The Dr Ambedkar interest subsidy scheme supports OBC and EWS students similarly. When comparing loans, factor in the subsidy — a headline rate of 10 per cent with full moratorium subsidy beats a 9 per cent rate without one.
How to apply: step by step
- Get admission first: banks need the admission letter and fee structure — apply for the loan as soon as admission is confirmed.
- Choose the bank: compare public sector banks (lower rates, subsidy access) with private lenders and NBFCs (faster processing, higher rates).
- Documents: admission proof, fee schedule, academic records, KYC of student and co-applicant (usually a parent), income proof, and collateral documents for larger loans.
- Vidya Lakshmi portal: the government’s common portal lets you apply to multiple banks with one form — use it.
- Sanction and disbursement: banks disburse directly to the institution, semester by semester — plan for processing time of 2-6 weeks.
Borrowing smart: rules families should follow
First, borrow only the gap — the amount after scholarships, savings and family contribution — not the maximum offered. Second, prefer shorter tenures you can afford; every extra year adds lakhs in interest. Third, understand floating vs fixed rates and the reset clauses. Fourth, the co-applicant parent should grasp the liability: it is joint. Fifth, start repaying interest during the study period if possible — even small payments dramatically cut the total interest. Sixth, never borrow for a course with poor placement outcomes without a brutally honest ROI calculation: loan EMI versus realistic starting salary.
What if repayment becomes difficult?
Banks offer restructuring for genuine hardship — contact the bank before defaulting, not after. Education loans cannot be wished away; default damages the CIBIL scores of both student and co-applicant, affecting future borrowing. If the degree does not lead to expected income, consider the bank’s rehabilitation options, and remember that the Section 80E deduction continues to soften the burden. The worst strategy is silence — banks negotiate with communicative borrowers far more readily than with absconders.
FAQs
Can I get a loan for studying abroad? Yes — banks offer overseas education loans, typically requiring collateral for larger amounts, with the same moratorium structure.
Does the loan cover living expenses? Yes — hostel, food, books, laptop, travel and insurance are all admissible components.
What is the maximum loan amount? There is no fixed ceiling; banks assess based on the course, institution and repayment capacity, with premier-institute students accessing the largest sanctions.
An education loan is not debt — it is leverage on your own future earnings. Borrow wisely, use the subsidies, repay diligently, and let the degree pay for itself.
Compiled by the Khabar 24h Editorial Desk from publicly available sources.
Related stories
View all →
CBSE Announces Special Class 12 Exams for Gulf Students
The Central Board of Secondary Education (CBSE) will hold special Class 12 examinations for students in seven West Asian countries whose 2026…
IIT Bombay Suicide: Family Alleges Police Pressure
The family of an IIT Bombay student who died by suicide alleges police tried to move them out of Mumbai; the police…
1,700 Errors in Odisha School Textbooks: What Happened
A probe is underway into how 1,700 errors slipped into Odisha school textbooks, exposing serious gaps in the state's quality checks.

Khabar 24h Editorial Desk — our explainers are prepared by the Khabar 24h editorial team using AI-assisted research tools, and every piece is reviewed by a human editor before publishing. We do not claim original reporting: our work is turning complex topics into simple, accurate summaries. Spotted an error? Write to contact@khabar24h.com — our corrections policy aims for same-day review.
More from this author →