What Happens to Your Money If Your Bank Fails: DICGC Deposit Insurance Explained
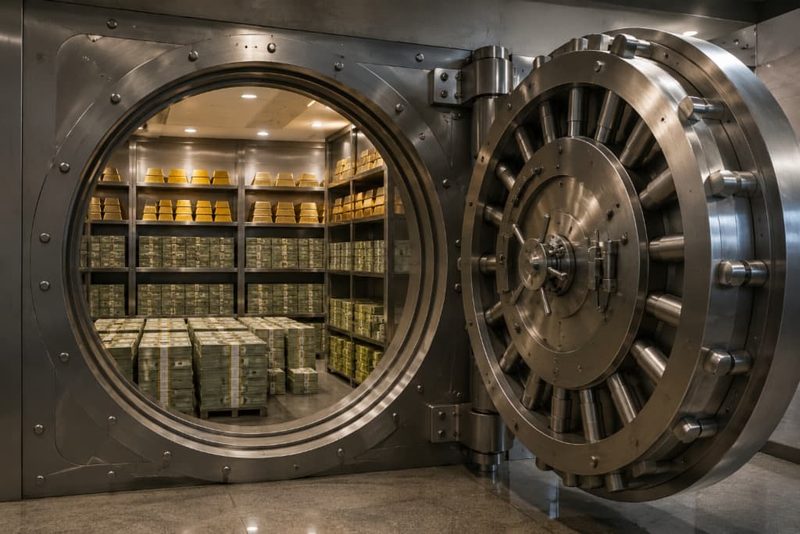
It is the nightmare every depositor quietly harbours: the bank holding your savings collapses, and your money vanishes with it. In India, that nightmare has a backstop. The Deposit Insurance and Credit Guarantee Corporation — the DICGC, a wholly owned subsidiary of the Reserve Bank of India — insures bank deposits up to 5 lakh rupees per depositor per bank, covering both principal and interest. Understanding this deposit insurance, what it covers and how payouts work, turns a vague anxiety into a concrete plan.
What the DICGC is and what it covers
The DICGC insures deposits held with commercial banks, regional rural banks, local area banks and cooperative banks licensed by the RBI. Coverage extends to savings accounts, fixed deposits, recurring deposits and current accounts — essentially every standard deposit product — up to a maximum of 5 lakh rupees per depositor in the same bank, including both principal and accrued interest. If you hold a 4 lakh rupee fixed deposit and a 2 lakh rupee savings balance in one bank, you are insured for 5 lakhs, not 6. But deposits in different banks are insured separately: 5 lakhs in Bank A and 5 lakhs in Bank B means 10 lakhs of total cover. The insurance premium — currently 12 paise per 100 rupees of deposits per half-year — is paid by the banks themselves, not by you; you are covered automatically.
What is not covered
The exclusions matter as much as the cover. Deposits of foreign governments, deposits of the central and state governments, and inter-bank deposits are outside the scheme. Money held in mutual funds, stocks or insurance policies is not a bank deposit and carries no DICGC cover — a common confusion. Deposits with non-banking finance companies are not insured either, which is worth remembering when NBFC fixed deposits advertise attractive rates. Also note the per-bank aggregation: holding multiple accounts in the same bank does not multiply your cover, but accounts held in different capacities — say, an individual account and a joint account where you are the first holder — can be treated separately under the rules.
How payouts actually work
When the RBI cancels a bank’s licence or a bank goes into liquidation or merger, the DICGC steps in. Following legislative changes in 2021, depositors get interim relief fast: the Corporation must pay up to the insured amount within 90 days of the RBI imposing restrictions such as a moratorium. In practice, the failed bank submits depositor data, the DICGC verifies it, and payments flow to depositors’ accounts — as seen in recent cooperative bank failures, where depositors received their insured sums without the years-long waits of the past. Amounts above 5 lakhs become claims against the liquidated bank’s assets, recovered — if at all — over a much longer process, and often only partially.
- Cover limit: 5 lakh rupees per depositor per bank, principal plus interest.
- Automatic: no enrolment needed; banks pay the premium.
- Speed: interim payment within 90 days of restrictions being imposed.
- Above the limit: excess amounts are claims in liquidation, recovered slowly and partially.
The practical strategy: spread large deposits
The 5 lakh cap makes the strategy obvious for anyone holding large cash balances: split deposits across multiple banks so that no single bank holds more than the insured amount in your name. A 20 lakh rupee corpus split across four banks is fully insured; kept in one bank, 15 lakhs of it rides on the bank’s survival. Prefer banks with strong capital adequacy and clean asset quality for the bulk of your money, and treat unusually high deposit rates from weak institutions as the risk premium they are. For most salary earners with modest balances, the insurance simply means one less thing to worry about — your emergency fund and short-term savings are protected by default.
FAQs
Are joint accounts insured separately? Generally yes — deposits held in different rights and capacities are insured separately, so a joint account can carry its own 5 lakh cover apart from your individual accounts, subject to the fine print.
Does DICGC cover NBFC deposits? No. Only deposits with banks — commercial, rural, local area and licensed cooperative banks — are covered.
Has the 5 lakh limit changed? It was raised from 1 lakh to 5 lakhs in February 2020, and there has been periodic public discussion of raising it further, but 5 lakhs remains the limit in 2026.
Bank failures are rare in India, and the regulatory record of protecting small depositors is strong. The DICGC’s 5 lakh rupee guarantee means ordinary savings are safe by design — and for larger sums, the simple discipline of spreading deposits across banks converts a catastrophic risk into a managed one.
Compiled by the Khabar 24h Editorial Desk from publicly available sources.
Related stories
View all →
GDP Up 7.8%, Taxes Soar: India’s Economy in High Gear
India’s economy is running at full speed. GDP grew 7.8% year-on-year in the April-June quarter, stronger than expected, driven by investment demand,…
Tata Sons Listing Row: Trusts Not Briefed on RBI Talks
Tata Trusts were reportedly not adequately briefed on Tata Sons' talks with the RBI over its listing mandate, adding a fresh twist…
Oil Firms Lose Rs 500 Crore Daily: Why OMCs Bleed Cash
India's oil marketing companies are losing over Rs 500 crore a day as crude costs outpace frozen retail fuel prices, straining their…

Khabar 24h Editorial Desk — our explainers are prepared by the Khabar 24h editorial team using AI-assisted research tools, and every piece is reviewed by a human editor before publishing. We do not claim original reporting: our work is turning complex topics into simple, accurate summaries. Spotted an error? Write to contact@khabar24h.com — our corrections policy aims for same-day review.
More from this author →